Understanding Loans For Bad Credit: A Comprehensive Examine
Introduction
In today’s economy, access to credit score plays an important position in each private finance and total economic progress. Nonetheless, people with dangerous credit score often discover themselves at a big drawback when looking for loans. Unhealthy credit can come up from various elements, including missed funds, high debt-to-revenue ratios, or bankruptcies. This report goals to supply a detailed examination of the panorama for loans available to people with bad credit score, together with types, terms, lenders, and the implications of taking on such loans.
Understanding Bad Credit
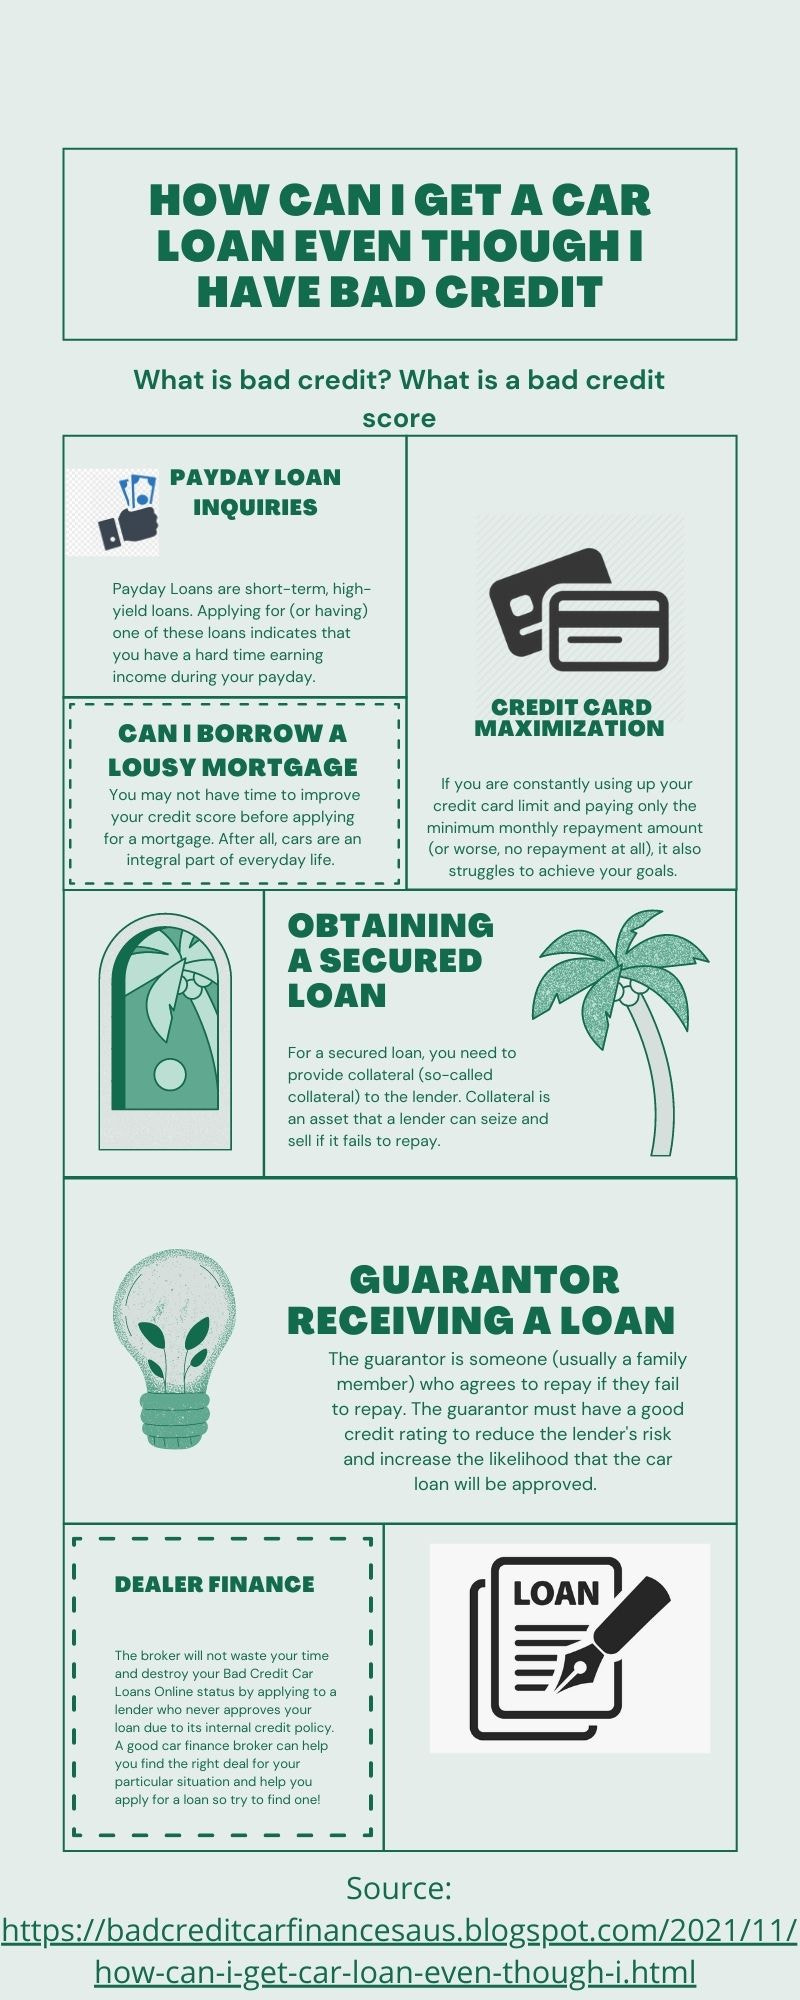
Dangerous credit is often defined by a low credit rating, which may be measured by various credit score scoring fashions, with scores underneath 580 usually considered as "poor". Credit scores are impacted by a number of components together with cost history, credit utilization, size of credit score historical past, kinds of credit score in use, and new credit score inquiries. Individuals with scores in the dangerous credit vary may face greater curiosity rates on loans, fewer borrowing options, and stricter approval criteria than these with good credit.
Types of Loans Accessible for Unhealthy Credit
1. Personal Loans
Personal loans for bad credit are provided by varied lenders, together with traditional banks, credit score unions, and on-line lenders. These loans can be unsecured or secured with collateral. Secured loans may be simpler to obtain but come with the chance of losing the asset used as collateral. Interest rates on personal loans for bad credit will be considerably larger than these offered to borrowers with good credit.
2. Payday Loans
Payday loans are short-term, high-interest loans designed to cover emergency bills until the borrower’s subsequent paycheck. Whereas they're accessible for people with dangerous credit score, the extremely high fees and curiosity rates make them a risky choice. These loans can result in a cycle of debt if borrowers battle to repay them on time.
3. Title Loans
Title loans enable borrowers to secure a loan using their automobile as collateral. The loan quantity relies on the car’s value, and borrowers maintain possession of the vehicle. Like payday loans, title loans come with excessive-interest charges and can result in lenders repossessing the car if funds are missed.
4. Peer-to-Peer Loans
Peer-to-peer lending platforms join borrowers directly with individual lenders. While some peers could assess credit score threat less stringently than traditional monetary institutions, the rates can fluctuate extensively. People with dangerous credit score should safe loans, but the phrases might not always be favorable.
5. Secured Credit score Playing cards
Although not a loan in the normal sense, secured credit score cards can help people rebuild their credit score. A secured credit card requires a cash deposit that serves because the credit score restrict. Making on-time funds can gradually enhance a borrower's credit score rating, opening up extra loan choices sooner or later.
The right way to Qualify for a Loan with Bad Credit score
Qualifying for loans with bad credit often requires demonstrating the power to repay the loan despite a poor credit score historical past. Lenders might consider elements similar to:
- Income Verification: Proof of consistent earnings helps reassure lenders of the borrower's capability to make payments.
- Employment Stability: A gradual job history could influence lending choices, because it suggests reliability.
- Debt-to-Earnings Ratio: A lower ratio signifies to lenders that a person might have more capability to absorb further debt.
- Collateral: Offering collateral can generally improve the probabilities of approval, particularly for secured loans.
The Role of Lenders
Lenders specializing in bad credit loans include:
- Traditional Banks: Some banks supply personal loans however typically require higher credit score scores for approvals.
- Credit Unions: These non-profit financial institutions may have more lenient requirements for existing members.
- Online Lenders: A rapidly rising sector, online lenders often have streamlined applications and can present fast decisions on loans.
- Payday Loan Suppliers: While accessible, these loans carry important dangers because of excessive costs.
Risks and Considerations
While acquiring a loan with unhealthy credit score is feasible, it comes with appreciable dangers:
- High-Curiosity Charges: Borrowers might encounter exorbitant interest rates that complicate repayment and increase the total amount owed.
- Loan Scams: People with dangerous credit could also be focused by predatory lenders with misleading practices. It is imperative to research lenders totally and consider their reputations.
- Debt Cycles: High short-term loans, like payday or title loans, can promote cycles of borrowing as people may battle to repay, resulting in additional debt.
- Affect on Credit score Rating: Making use of for multiple loans may end in onerous inquiries, which might quickly lower credit score scores.
Methods for Securing Loans Responsibly
- Analysis and Compare: Earlier than committing, it is essential to match a number of lenders, interest charges, charges, and terms.
- Consider a Co-signer: If attainable, having a co-signer with better credit can improve possibilities of loan approval and yield higher rates.
- Begin with Quick-Term Loans: Choosing smaller loan quantities or shorter phrases might assist minimize complete interest prices.
- Search Alternate options: Examine emergency funds, neighborhood applications, or family loans as potential alternate options to excessive-threat loans.
- Rebuild Credit First: Taking steps to enhance credit score scores—like paying bills on time or lowering excellent debts—can lead to raised loan options in the future.
Conclusion
Securing a loan with dangerous credit score is fraught with challenges, yet it's not not possible. Borrowers should navigate a panorama full of high prices and potential risks. Awareness of lending choices, diligent research, and accountable borrowing practices can aid individuals in making informed monetary decisions. Building credit over time can't solely improve entry to better loans but additionally offer a pathway toward larger financial stability. By understanding the nuances of loans out there for unhealthy credit, people can take steps to regain control over their monetary futures.
등록된 댓글이 없습니다.